Quick Summary
Real estate remains one of the most reliable asset classes for building generational wealth due to its inherent scarcity and utility. This article examines how strategic property acquisition, combined with market timing and financial leverage, creates a robust foundation for financial independence. We explore the mechanics of capital appreciation, the significance of location selection, and the role of professional property management in maximizing returns for long-term holders.
Establishing the Financial Foundation Through Real Estate
The pursuit of financial independence often leads individuals toward various investment vehicles, yet few possess the historical consistency of physical property. Unlike volatile equities or low-yield fixed deposits, real estate offers a tangible asset that serves both a functional and financial purpose. The primary driver of wealth here is the limited supply of land. As populations expand and urban centers become more crowded, the demand for well-located parcels and developed spaces increases. This fundamental economic principle ensures that over extended horizons, property values tend to outpace inflation, preserving and increasing the purchasing power of the owner. Heritage Prime observes that investors who prioritize long-term holding periods over speculative short-term flips often see the most significant compounding effects on their initial capital outlay.
How does property act as a hedge against inflation?
Inflation erodes the value of currency, making everyday goods and services more expensive over time. However, real estate typically responds positively to inflationary pressures. As the cost of construction materials, labor, and land increases, the replacement cost of existing buildings rises, pushing up market values. Additionally, rental income is not static. Landlords can adjust lease agreements periodically to reflect current market conditions, ensuring that the cash flow generated by the asset maintains its real value. This dual benefit of asset price growth and rising income makes property a preferred choice for those looking to protect their wealth from the devaluing effects of a weakening currency. Understanding these dynamics is easier when following the latest property market updates which highlight regional trends and economic shifts affecting valuation.
The Mechanics of Long-Term Capital Appreciation
Capital appreciation is the increase in the market value of a property over the price at which it was originally purchased. While market fluctuations occur in the short term, the long-term trajectory for real estate in developing economies and growing metropolitan areas is historically upward. This growth is rarely accidental. It is often fueled by significant infrastructure developments such as new highways, metro lines, or industrial hubs. When an area becomes more accessible or gains better connectivity to employment centers, the desirability of the local real estate surges. Investors who can identify these emerging zones before they reach full maturity stand to gain the most substantial rewards. The process requires patience and a deep understanding of urban planning cycles.
What role does infrastructure play in property value?
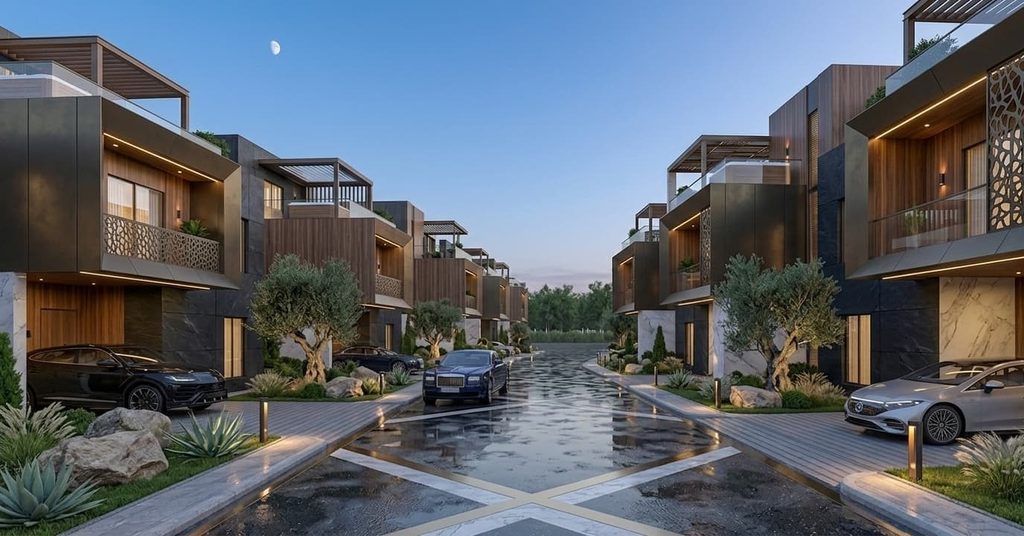
Infrastructure is the lifeblood of real estate valuation. A residential plot located in a remote area might have low intrinsic value today, but the announcement of a nearby international airport or a major commercial park can trigger a rapid revaluation. Public investments in roads, water supply, and sewage systems transform raw land into habitable and productive spaces. This transformation is what drives massive equity growth for early investors. By keeping an eye on government master plans and regional development boards, savvy property owners can position their portfolios in the path of growth. For instance, high-end developments like the Ayodhya Enclave luxury villa project are often situated in corridors where future growth is anticipated, providing both lifestyle benefits and strong potential for value increase.
Maximizing Returns Through Rental Yields and Cash Flow
While appreciation focuses on the future sale price, rental yield provides the immediate liquidity needed to sustain the investment. Rental yield is calculated as the annual rent received as a percentage of the property’s total cost. In many urban markets, residential yields range from 2 percent to 4 percent, while commercial properties can offer significantly higher returns. Achieving a positive cash flow, where the rental income exceeds the mortgage payments and maintenance costs, is the gold standard of property ownership. This steady stream of income can be reinvested into other assets or used to pay down debt faster, further accelerating the wealth-building process. Consistent occupancy is key to this strategy, making the choice of property type and tenant profile critical decisions.
Are independent homes better for rental income than apartments?
The choice between independent homes and high-rise apartments depends on the target demographic. Independent homes often attract families or corporate tenants looking for privacy and space, leading to longer lease durations and lower turnover rates. These properties also offer the unique advantage of land ownership, which typically appreciates faster than the building structure itself. In growing suburban regions, independent homes with modern amenities represent a hybrid of lifestyle comfort and investment security. These assets often command premium rents due to their scarcity compared to the mass-produced apartment units found in dense city centers. The ability to modify or expand an independent structure also provides owners with the flexibility to increase the property’s value through physical improvements.
| Feature | Residential Property | Commercial Property |
|---|---|---|
| Average Yield | 2-4% | 6-9% |
| Lease Term | 11-24 Months | 3-9 Years |
| Maintenance | Landlord/Tenant Mix | Often Tenant (Net Lease) |
| Risk Profile | Lower Volatility | Higher Vacancy Risk |
Leveraging Capital for Exponential Growth
One of the most powerful tools in real estate is financial leverage. This involves using borrowed capital to increase the potential return on an investment. If an investor puts down 20 percent of a property’s value and the property appreciates by 10 percent, the investor has effectively earned a 50 percent return on their actual cash investment, excluding interest costs. This ability to control a large, high-value asset with a relatively small amount of personal capital is unique to real estate. Over time, as the mortgage is paid down by the tenant’s rent and the property value rises, the owner’s equity grows exponentially. This equity can eventually be used as collateral for further acquisitions, creating a snowball effect of wealth accumulation.
What are the risks of over-leveraging?
While leverage can magnify gains, it also increases vulnerability during market downturns. If property values fall or interest rates rise sharply, an over-leveraged owner might find themselves with negative equity or an inability to meet debt obligations. Successful long-term investors manage this risk by maintaining healthy debt-to-income ratios and ensuring they have sufficient cash reserves to cover periods of vacancy. It is also important to understand the legalities surrounding financing and ownership. Reviewing our real estate transaction terms helps investors understand the responsibilities and protections afforded to them during the acquisition process. Sound financial planning ensures that the use of debt remains a tool for growth rather than a source of instability.
Tax Advantages and Wealth Preservation
Governments often use the tax code to encourage property ownership, recognizing its role in economic stability and housing provision. Property owners can benefit from various deductions, including mortgage interest, property taxes, and depreciation. Depreciation is particularly notable because it is a non-cash expense that reduces taxable income without affecting the actual cash flow of the property. When a property is eventually sold, capital gains tax treatments are often more favorable than those for ordinary income, especially if the asset has been held for several years. Strategic use of these tax benefits can significantly increase the net after-tax return on an investment, allowing more wealth to be preserved across generations.
How does the holding period affect tax liabilities?
The duration for which a property is held is a primary factor in determining the tax rate on any gains. Short-term capital gains are usually taxed at the owner’s marginal income tax rate, which can be quite high for successful professionals. In contrast, long-term capital gains often benefit from indexation, which adjusts the purchase price for inflation, thereby reducing the taxable profit. This provides a strong incentive for investors to adopt a multi-decade perspective rather than seeking quick profits. Additionally, many jurisdictions allow for the deferral of taxes if the proceeds from a sale are reinvested into another property. This allows an investor to move up the property ladder, trading smaller assets for larger, more productive ones without losing a significant portion of their capital to the tax authorities.
Diversification Within the Real Estate Asset Class
A well-rounded wealth creation strategy involves diversification not just across different asset classes like stocks and bonds, but within the real estate portfolio itself. Owning different types of property in various geographic locations can protect against localized economic downturns. For example, while a commercial office space might face challenges during a shift toward remote work, residential demand in suburban townships often remains resilient. Similarly, land banking in the periphery of a growing city offers high growth potential, while an established apartment in a city center provides stable, immediate income. By spreading investments across different segments, an owner can balance the need for liquidity, income, and growth.
Why is geographic diversification important?
Regional economies do not move in perfect unison. A slowdown in the technology sector might impact real estate in one city, while a boom in manufacturing or tourism might drive growth in another. By owning assets in different markets, an investor ensures that their entire net worth is not tied to the fate of a single municipality. This strategy also allows investors to capitalize on different stages of the urban development cycle. Some regions might be in a phase of rapid infrastructure expansion, offering high appreciation, while others are mature markets offering high-quality tenants and reliable yields. A balanced approach reduces the overall volatility of the portfolio and ensures a more predictable path toward long-term wealth targets.
The Importance of Professional Property Management
Ownership is not a passive endeavor. To maintain and grow the value of an asset, active management is required. This includes regular maintenance to prevent physical deterioration, proactive tenant relations to ensure high retention, and periodic renovations to keep the property competitive in the market. Neglected properties often see a decline in both rental income and market value. For those who do not have the time or expertise to manage properties personally, hiring a professional management firm is a wise investment. These firms handle the day-to-day operations, from screening tenants to managing repairs, ensuring that the asset continues to perform at its peak without requiring constant attention from the owner.
Can renovations truly increase the ROI of an old property?
Strategic upgrades are one of the fastest ways to force appreciation. Simple improvements like modernizing a kitchen, updating bathroom fixtures, or improving the curb appeal through landscaping can significantly increase the perceived value of a home. For commercial spaces, upgrading to energy-efficient lighting and smart building systems can attract higher-paying corporate tenants and reduce operating costs. The key is to ensure that the cost of the renovation does not exceed the projected increase in value or rent. By focusing on high-impact areas that matter most to tenants and buyers, property owners can actively manufacture equity rather than simply waiting for the market to rise. This proactive approach distinguishes successful real estate moguls from passive landlords.
Frequently Asked Questions
Is real estate better than the stock market for long-term wealth?
Real estate and stocks serve different purposes in a portfolio. While stocks offer higher liquidity and historical returns that are competitive, real estate provides lower volatility, tangible utility, and the ability to use leverage. Property also offers a more direct hedge against inflation and the psychological security of owning a physical asset. Most wealthy individuals use a combination of both to achieve balanced growth.
What is the ideal holding period for a property investment?
For maximum wealth creation, a holding period of 7 to 10 years is often considered the minimum. This allows enough time to ride out market cycles, recover transaction costs like stamp duty and brokerage, and benefit from significant capital appreciation. Many generational wealth builders choose to never sell their core assets, instead using them to generate perpetual income.
How do I start investing in real estate with limited capital?
Investors with limited capital can look into fractional ownership, real estate investment trusts (REITs), or partnering with others in a syndicate. Additionally, purchasing smaller residential plots in emerging areas or utilizing government-backed loan programs for first-time buyers can provide an entry point into the market. Starting small and gradually trading up as equity grows is a proven path to large-scale ownership.
What are the biggest mistakes to avoid in property ownership?
The most common mistakes include overpaying for a property due to emotional attachment, neglecting due diligence on legal titles, and failing to account for ongoing maintenance costs. It is also vital to avoid buying in areas with declining populations or lack of economic diversity. Always ensure that the investment aligns with your long-term financial goals and that you have a clear exit or management strategy in place.