Quick Summary
Real estate investment demands a sophisticated understanding of how capital appreciation and rental yield balance against inherent market risks. Investors must prioritize thorough research, demographic analysis, and local infrastructure developments. This guide breaks down the essential components of risk mitigation, the financial dynamics of leverage, and the strategic selection of property types to ensure sustainable growth in a complex economy.
Understanding Real Estate Market Dynamics
What drives property valuation over long durations?
Market values in real estate are rarely static. They respond to a variety of macro and micro-economic factors that influence supply and demand. At a macroeconomic level, interest rates set by central banks dictate the affordability of credit. When borrowing costs remain low, capital flows into real estate assets, pushing prices upward as more buyers enter the market. Conversely, high-interest rate environments often suppress buyer activity, forcing investors to look for properties with significant cash flow potential to hedge against stagnant capital growth.
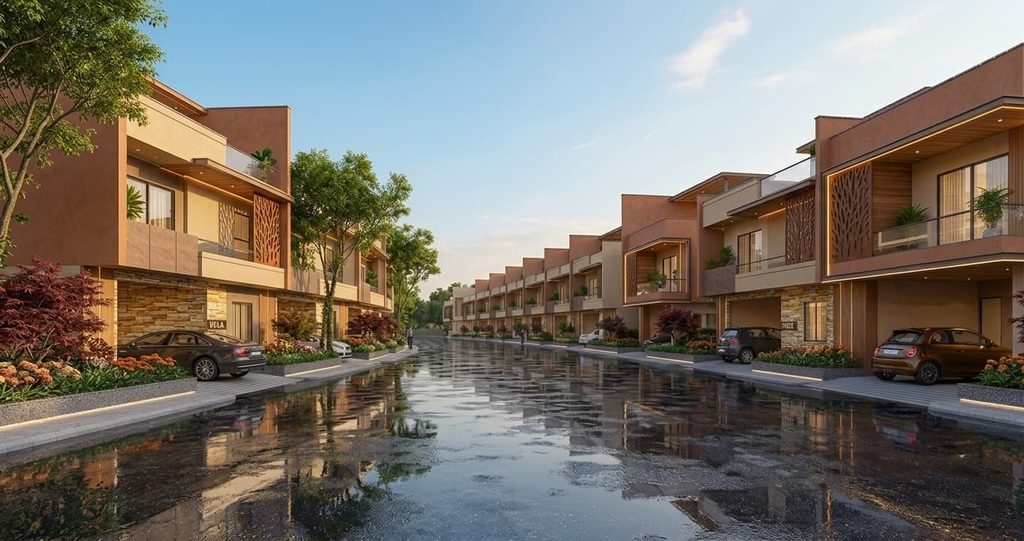
Micro-economic factors, such as local job growth, infrastructure projects, and neighborhood gentrification, often play a more significant role in localized property performance. An area experiencing high employment expansion will naturally see increased demand for residential space. Smart investors monitor these specific indicators before committing capital. Furthermore, the availability of high-quality inventory, such as premium villas for sale, acts as a primary indicator of luxury segment health. A neighborhood with robust development pipelines and planned connectivity improvements typically holds its value better during market downturns than regions lacking such foundational support.
How to identify emerging growth zones
Identifying an area before it peaks involves looking at historical census data alongside planned government expenditures. Often, the presence of new educational institutions or large-scale medical facilities serves as a catalyst for long-term population growth. These anchors pull in skilled workers and service professionals, creating an immediate and sustainable need for diverse housing solutions. Property values in these zones rarely plummet because the underlying demand remains tied to essential services.
Mitigating Financial and Structural Risk
Managing debt exposure and leverage
Leverage is a dual-purpose tool in real estate. It allows an investor to control a larger asset base with a smaller amount of personal capital, effectively magnifying returns on equity. However, excessive debt creates significant vulnerability. When rental markets fluctuate, those with high loan-to-value ratios may struggle to cover mortgage obligations. A professional approach involves maintaining a reasonable debt service coverage ratio, ensuring that rental income comfortably exceeds interest payments even during periods of high vacancy.
Diversification remains the most effective strategy for risk reduction. Relying on a single asset type in one neighborhood leaves an investor exposed to localized volatility. Spreading risk across different asset classes, such as retail, commercial, or residential sectors, helps stabilize portfolios. For those seeking to secure their assets, adhering to strict user data protection guidelines during the acquisition and management phase is also a fundamental aspect of operating a professional investment firm. Protecting the integrity of the investment process from start to finish ensures that both the investor and the property management operations remain shielded from unnecessary liabilities.
The impact of due diligence
Due diligence in property acquisition is not merely about physical inspections. It involves a deep examination of legal titles, tax encumbrances, and zoning laws. Failure to verify these aspects can result in hidden costs that erode anticipated returns. Engaging with experts who understand the nuances of the local regulatory environment is a prerequisite for any successful acquisition. When exploring options like the independent homes with modern amenities available in master-planned communities, verify the developer’s track record and the long-term maintenance plans for the collective facility.
Analyzing Potential Returns and Wealth Creation
Rental yield versus capital appreciation
Investors must choose whether their strategy favors immediate cash flow or future capital gains. Rental yield is the income generated from a property relative to its purchase price, often expressed as a percentage. Properties in high-demand residential areas or those catering to corporate renters typically provide steady yields. Capital appreciation, on the other hand, relies on the property increasing in value over time. This is often driven by land scarcity, urban sprawl, or significant local economic development.
A balanced strategy often incorporates both elements. By acquiring assets in areas with strong rental demand that are also primed for future infrastructure upgrades, an investor captures cash flow during the holding period while waiting for the property to reach its peak appreciation potential. This approach minimizes the pressure to sell during market dips, as the rental income continues to provide a consistent return on investment.
Tax advantages in real estate
Real estate offers significant tax-deferred growth opportunities that other investment classes rarely match. Deductions for depreciation, property taxes, and mortgage interest allow owners to maintain a larger portion of their operational income. Smart investors plan their acquisitions around these structural benefits, working closely with financial advisors to structure their holding entities in ways that maximize fiscal efficiency. Understanding the difference between short-term capital gains and long-term holding strategies is essential for effective wealth preservation and accumulation.
Comparing Different Asset Classes
Residential versus commercial investing
Residential property is generally seen as a safer, more liquid asset class. Everyone needs shelter, which means the underlying demand remains consistent across economic cycles. However, margins are often tighter, and tenant management requires active, ongoing attention. Commercial properties offer longer lease terms and higher potential yields but are subject to broader market trends. When the business cycle weakens, office or retail spaces often experience higher vacancy rates compared to residential housing.
Consider the target demographic. Investing in high-end communities often attracts long-term, stable tenants who value amenities and property prestige. These assets typically require less frequent turnover and maintain better physical conditions over time. When deciding on the right entry point, you should contact seasoned property experts to gain a comprehensive understanding of current market absorption rates and upcoming project developments that may influence your specific asset choice.
The role of professional property management
Whether you manage your assets yourself or outsource the task, operational excellence is the key to minimizing risk. Efficient maintenance, timely rent collection, and rigorous tenant screening are the pillars of long-term profitability. Poor management results in high turnover, property neglect, and eventually, a decline in asset value. Treating real estate as a business rather than a passive income stream is the most common trait among successful property investors.
Navigating Long-Term Market Cycles
Identifying market peaks and troughs
Markets move in cycles defined by expansion, peak, contraction, and recovery. Understanding these phases prevents emotional decision-making. During the expansion phase, competition for properties is fierce, and pricing may outstrip rental income. This is often when investors must be most cautious about over-leveraging. During the contraction phase, panic selling can create opportunities for buyers with significant liquidity to acquire high-quality assets at deep discounts. Patience is the ultimate investment strategy in real estate.
Planning for economic disruptions
Economic disruptions are inevitable, but their impact on real estate can be mitigated through contingency planning. Maintaining an emergency reserve fund specifically for property maintenance and potential periods of vacancy is a basic requirement for prudent risk management. Avoid placing all capital in a single project. By laddering investments and staggering the maturity or development stages of your properties, you create a buffer against liquidity issues. A well-constructed portfolio is resilient to sudden changes in market conditions.
Frequently Asked Questions
How do I accurately calculate the potential ROI of a property?
Calculating ROI requires summing up your annual rental income, subtracting all operational expenses including maintenance, taxes, and insurance, and then dividing the net income by the total cash invested. Do not forget to account for potential vacancy periods and future renovation costs. For a more precise figure, calculate both the cash-on-cash return and the internal rate of return to understand the impact of your leverage and expected capital growth over your intended holding period.
What is the most common mistake new investors make?
The most frequent error is underestimating ongoing operational costs and overestimating potential rental growth. Many beginners fail to factor in major repairs, property management fees, or the possibility of prolonged vacancies. Another significant mistake is purchasing in an area without understanding the local demographic shift, which can lead to stagnant property values and difficulty in finding qualified, long-term tenants.
When is the best time to leverage a real estate asset?
Leveraging is most effective when the cost of borrowing is lower than the property’s cap rate or the expected rate of capital appreciation. You should only use significant debt when you have sufficient cash reserves to cover the mortgage during unexpected periods of low occupancy. If your net operating income is already covering the debt service by a comfortable margin, leveraging can be an effective way to grow your portfolio size.
Why is demographic research important for long-term investments?
Demographics dictate the demand for specific property types. An aging population may require smaller, low-maintenance housing, while an influx of young professionals often increases the demand for centrally located apartments or modern villas. By aligning your investment with the long-term trends of a specific region, you ensure that there will always be a ready supply of renters or future buyers, which significantly mitigates the risk of long-term property obsolescence.